A Merger of Equals
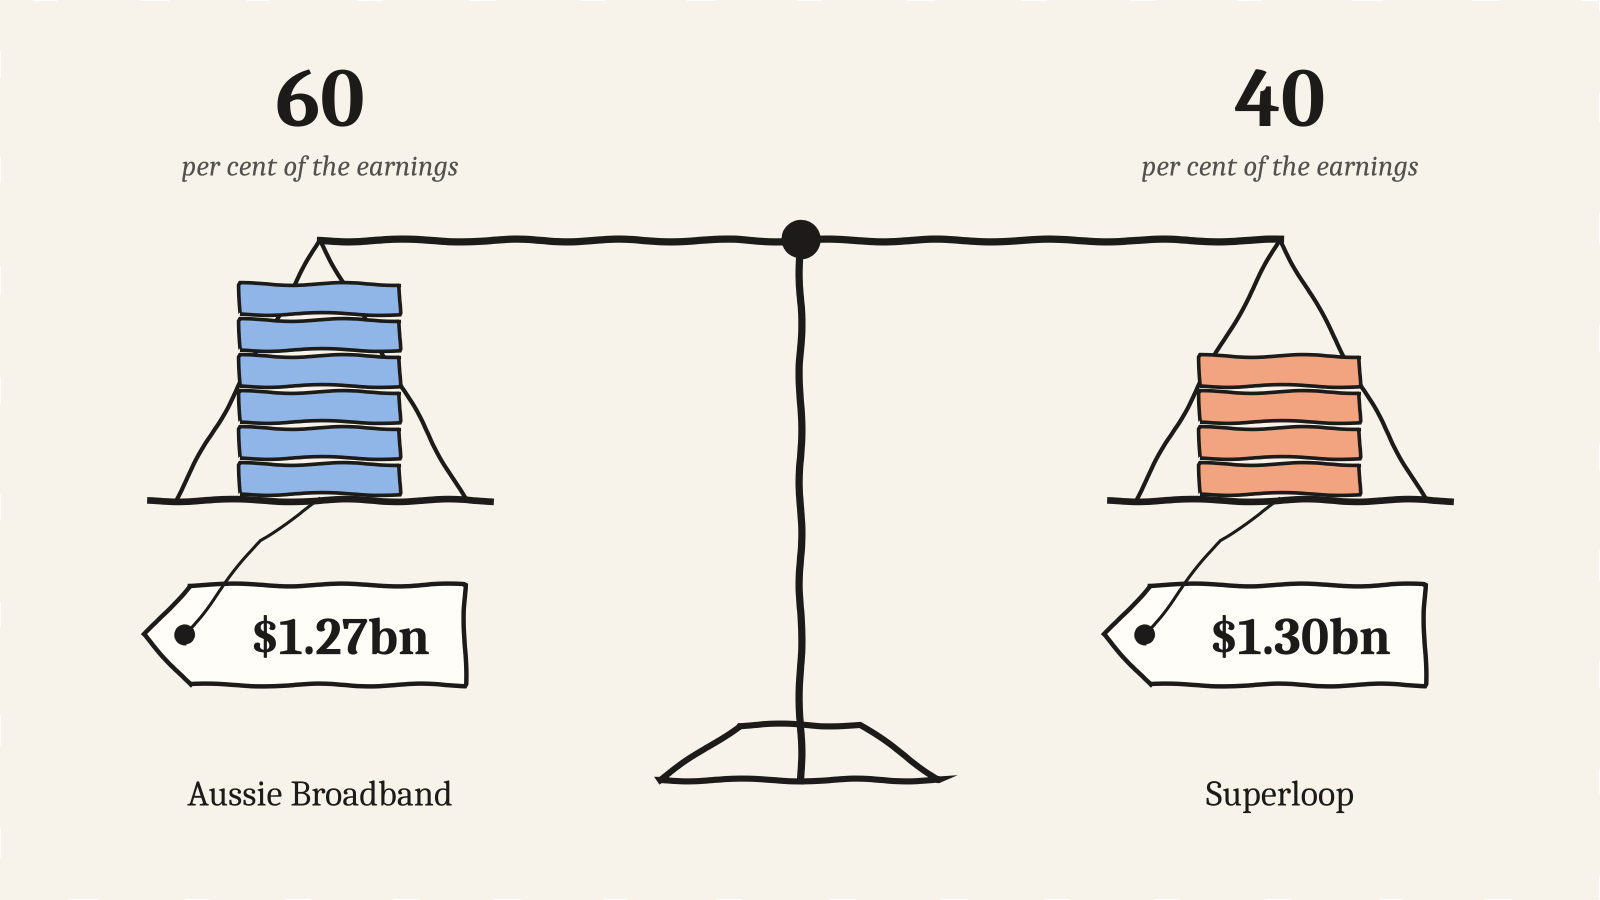
Same price, give or take $30 million. One earns half as much again.
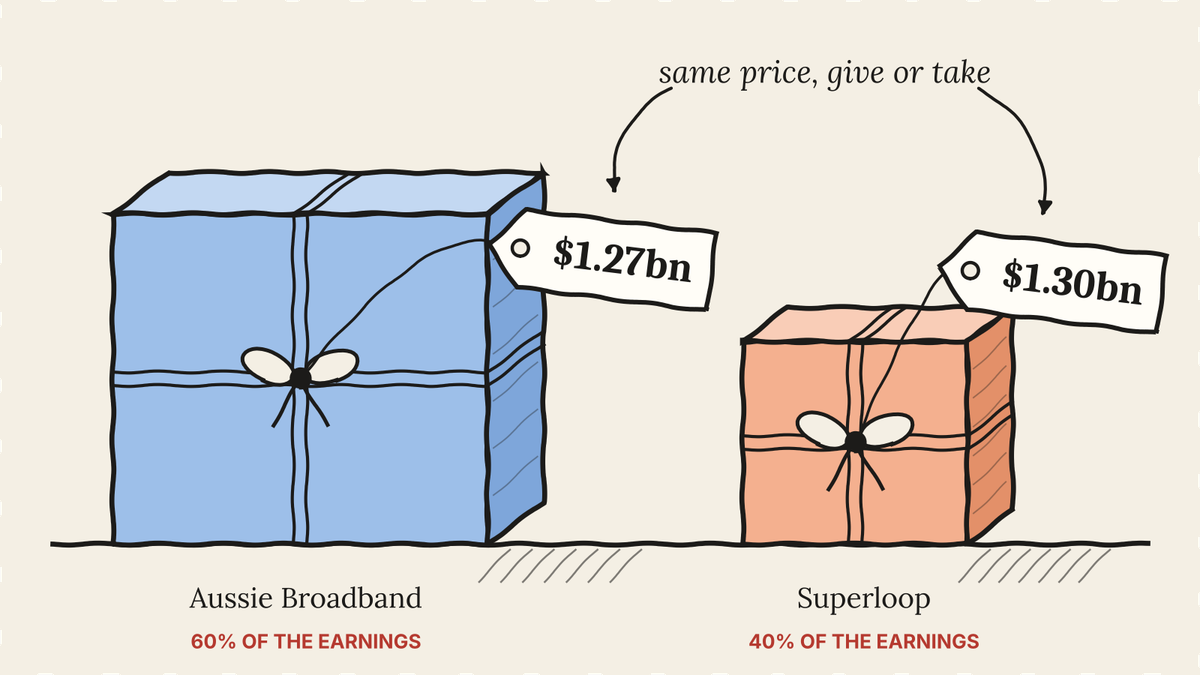
The market has weighed Aussie Broadband and Superloop and found them equal, to within $30 million. One of them earns half as much again as the other, which is the sort of detail a market can miss when it is busy.
Everybody with a telco and a LinkedIn account agrees they should merge. One pauses to admire that none of them has named a price. At the one on the screen, Aussie’s shareholders hand over nearly a fifth of their EBITDA before lunch. At any lower one, Superloop’s do not turn up.
In between stand an energy retailer with a footnote, another with clause 7.1, and a regulator contemplating half the gigabit tier. The last attempt was seen off by a rule about Singapore. Singapore approved the full stake five weeks after Aussie had been made to sell part of it.
There is no shortage of people who think Aussie Broadband and Superloop should merge.
People who run telcos have said so in public, more than once, since August.
Phillip Britt, who co-founded Aussie and actually tried it, agrees.
Aussie's own board agreed in February 2024, to the tune of $466 million, and was beaten by a rule about Singapore.
The logic has not moved. Two listed challengers buy the same wholesale product from NBN Co off the same price list, run two of everything else, and grow in large part by lifting big accounts off each other.
Origin Energy went from Aussie to Superloop. AGL, until now a Superloop customer, is going the other way.
These are not new customers. They are the same customers, moved, and paid for in scrip each time they move.
Unaudited has no quarrel with the logic. Logic is free.
This article concerns the paperwork, which is where they keep the price.
Opportunistic
Begin with the last attempt, because the record of it is public and nobody comes out of it looking quite the way they intended.
On 26 February 2024 Aussie offered to buy Superloop with its own paper: 0.21 of an Aussie share for every Superloop share, or roughly one Aussie share for every five. At Aussie's price that week, that valued a Superloop share at about 95 cents.
It also bought 19.9 per cent of the register for $92.9 million, to show that it meant it.
Superloop's board called the offer "opportunistic" and said it "fundamentally undervalues" the company.
Target boards say that the way other people say good morning.