First in Line
The chairman lent $38 million, secured it a day before the water rose, and took ticket one. Punctuality is a virtue.
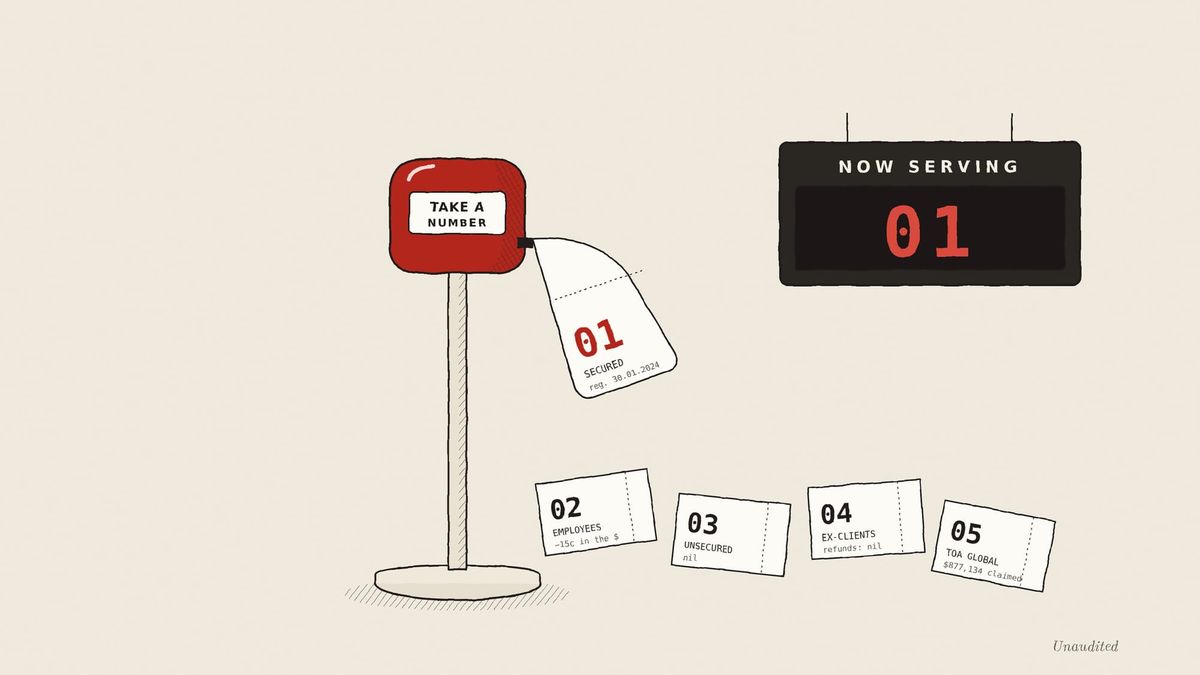
Retinue's chairman funded $38 million of losses, took security over everything the firm owned through a company bearing his initials, and stands first in line for what is left. By every account it was done properly. That is rather the point.
In an insolvency, the profit and loss statement tells you how a company died. The queue tells you who was standing closest to the body.
Last week, Unaudited set out how Retinue Accounting became Australia's fastest-growing accounting firm, lost $38.9 million in twenty-two months without once making a gross profit, and was sold for a dollar down. That was the story of the business.
This is the story of the money. Where it came from, how it was secured, and who is first in line now that it is gone.
It is, for the most part, a story about one man and a lending company associated with him. It is also a story in which, according to the administrators and liquidators, nothing was done that the law does not allow. Both of those things are true at the same time, and the second is rather more interesting than the first.
The Family Money
Retinue was never a venture-backed startup in the ordinary sense. There was no Series A, no syndicate, no board seat for a fund in San Francisco. There was a chairman with the means to pay for it.
According to the company's management accounts, as reported by the administrators, the business received about $38.01 million in funding from "a Director and the Secured Creditor." It arrived in three instalments:
- Loan 1: $20.47 million, most of it during FY24
- Loan 2, tranche 1: $7.62 million
- Loan 2, tranche 2: $9.92 million, all of it in the seven and a half months before the end