The Observable Price
Lawpath built a single source of truth. ASIC has the other one.
Every company keeps two accounts of itself. One is written for the market, in announcements and award citations. The other is lodged with the regulator, where nobody looks. Lawpath’s second account runs to eight extracts of its share register, and the story it tells is slower, cheaper and considerably less flattering.
§Right of reply
Questions were put in writing to Westpac Banking Corporation and to LegalZoom.com, Inc., with two working days to reply. Asked what either of them knew about this company before they paid for a piece of it, both went quiet.
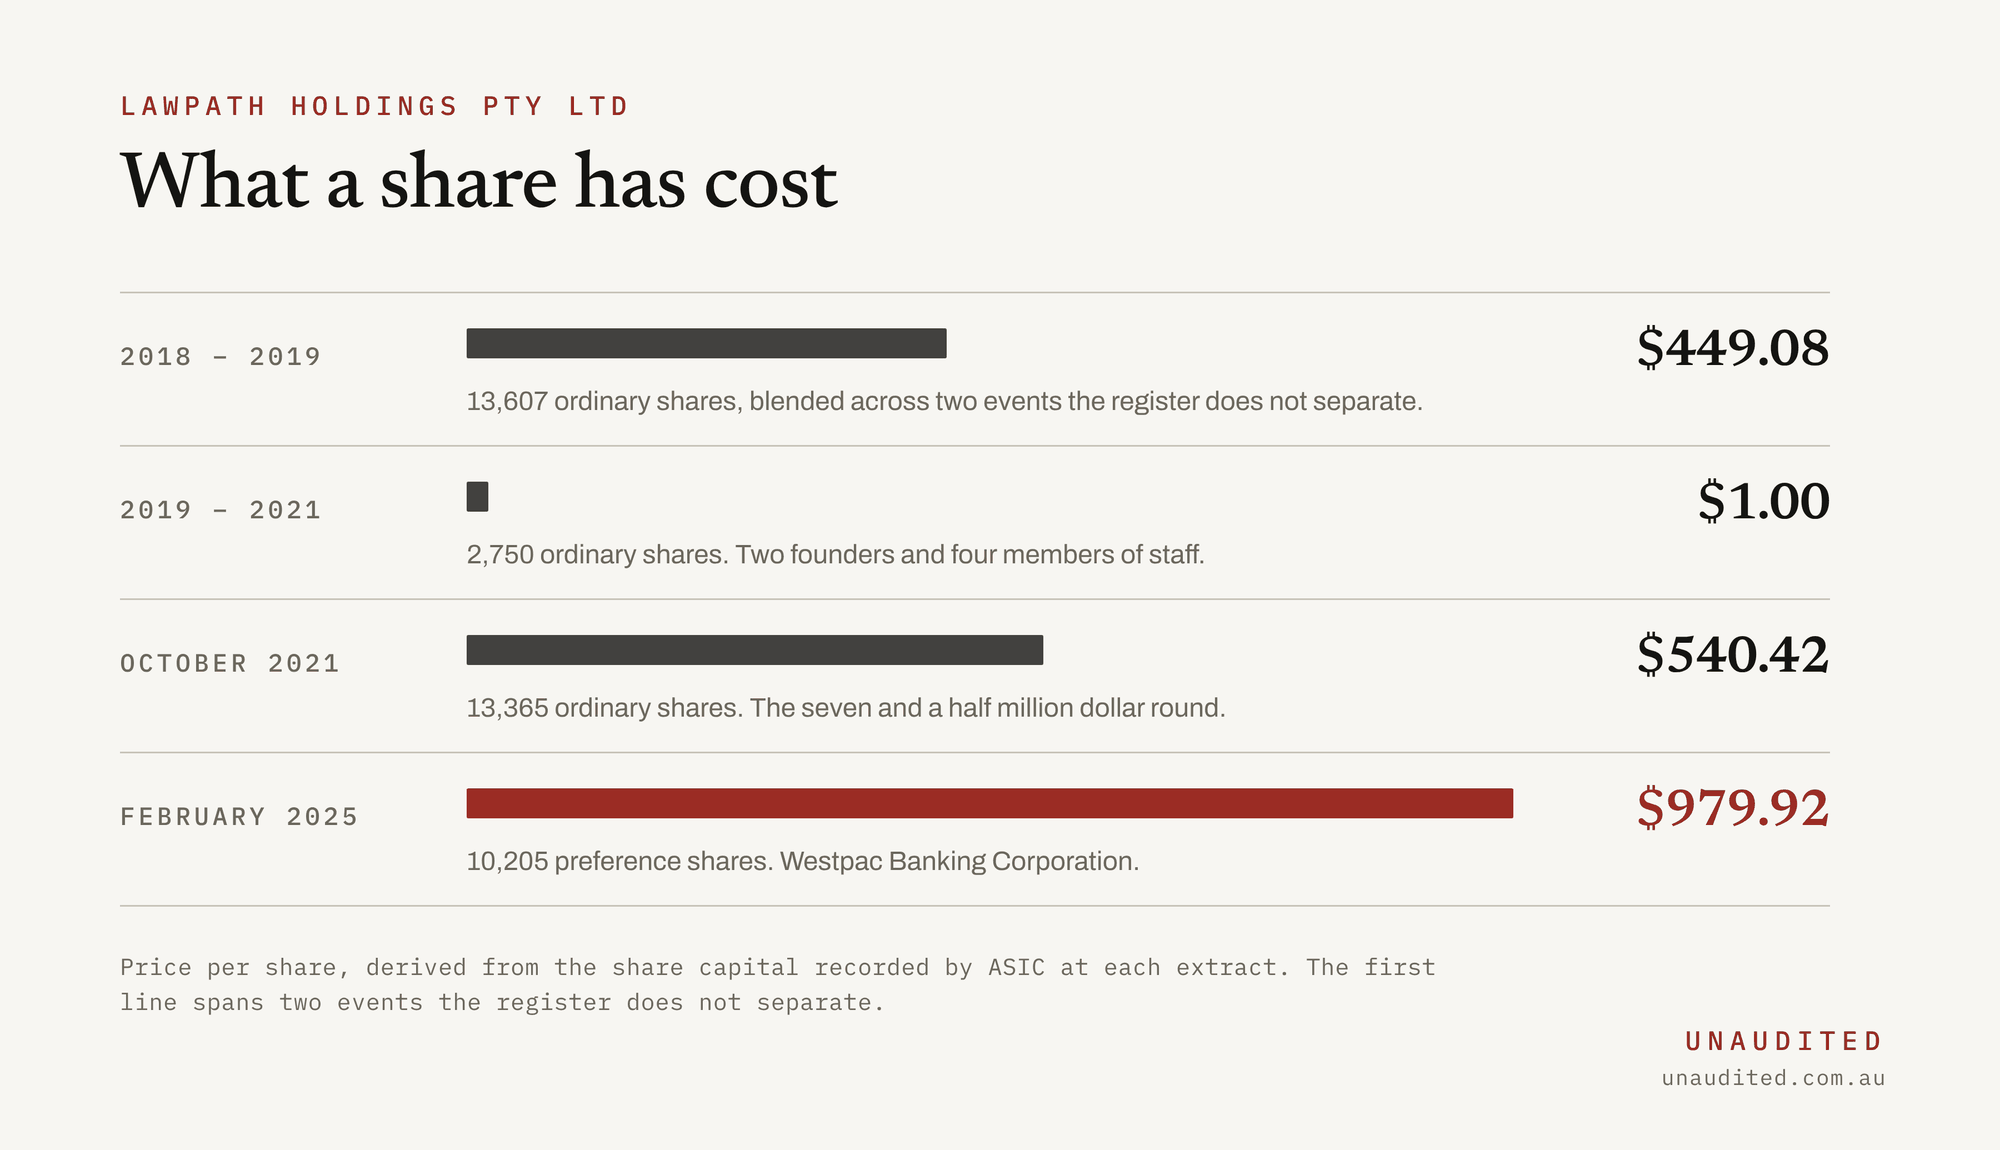
Part One established what Westpac paid for its preference shares, what that implied for the whole company, and the two caveats that go with the figure. It will not be rehearsed here.
What follows is what the rest of the register says, now that eight company extracts going back to 2018 have been reconciled line by line, and what one shareholder has had to tell a foreign regulator while everybody in Sydney was reading the press release.
The holder who has to file
LegalZoom.com, Inc. is listed on the Nasdaq. It is also, as Part One recorded, Lawpath's third-largest shareholder.
Being listed, it has to tell the United States Securities and Exchange Commission what it carries that holding at four times a year, whether or not anybody in Australia would like it to.
Be precise about what that figure is, because it is not a valuation. LegalZoom holds Lawpath under the measurement alternative for equity securities without a readily determinable fair value: cost, adjusted only when there is an impairment or an observable price change in an orderly transaction. Nobody in Glendale sits down each quarter and forms a view on what an Australian legal documents company is worth. The number sits where it sat until something outside moves it.
Something outside moved it once.
At 31 December 2024 LegalZoom carried the stake at US$4.4 million. At 31 March 2025 it carried it at US$4.7 million. The quarterly report puts the increase at $302,000, books it in the cash flow statement as a non-cash item rather than money spent, and explains itself in one sentence.
"The change in the carrying amount was due to an observable price change in an orderly transaction."
LegalZoom.com, Inc., Form 10-Q, Q1 2025
This post is for subscribers only
Preference
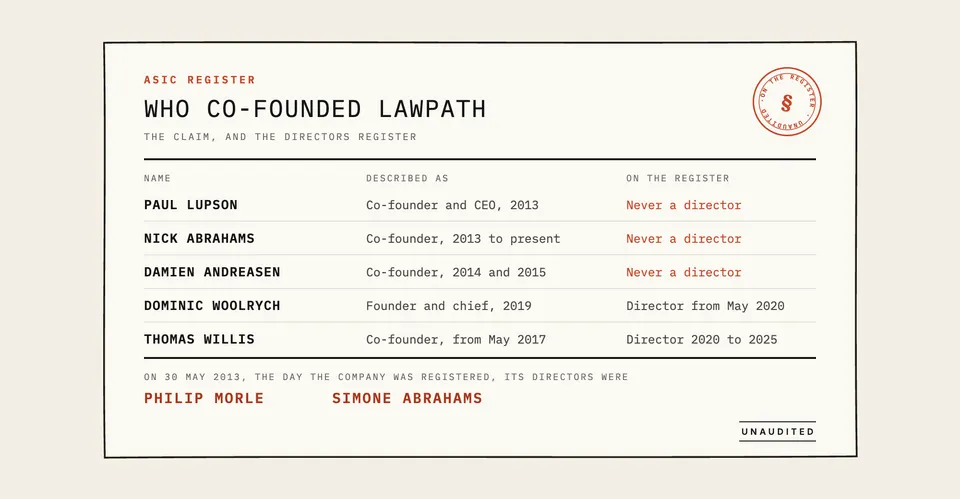
Lawpath sells the democratisation of law, from $39 a month. Its chief executive announced the revolution on a podcast titled Democratic Revolution, the month the bank’s shares were issued. It sells an ASIC compliance service, and told ASIC about its new director five months late. Five men are now called its founders. On the day it was registered, none of them had a chair. In 2025 Australia’s oldest bank bought a class of shares nobody else holds, and an observer’s chair to go with it. The press release said partnership. The register said preference. Democracy, at Lawpath, has a share class. The house always wins. This time it brought its own chair.